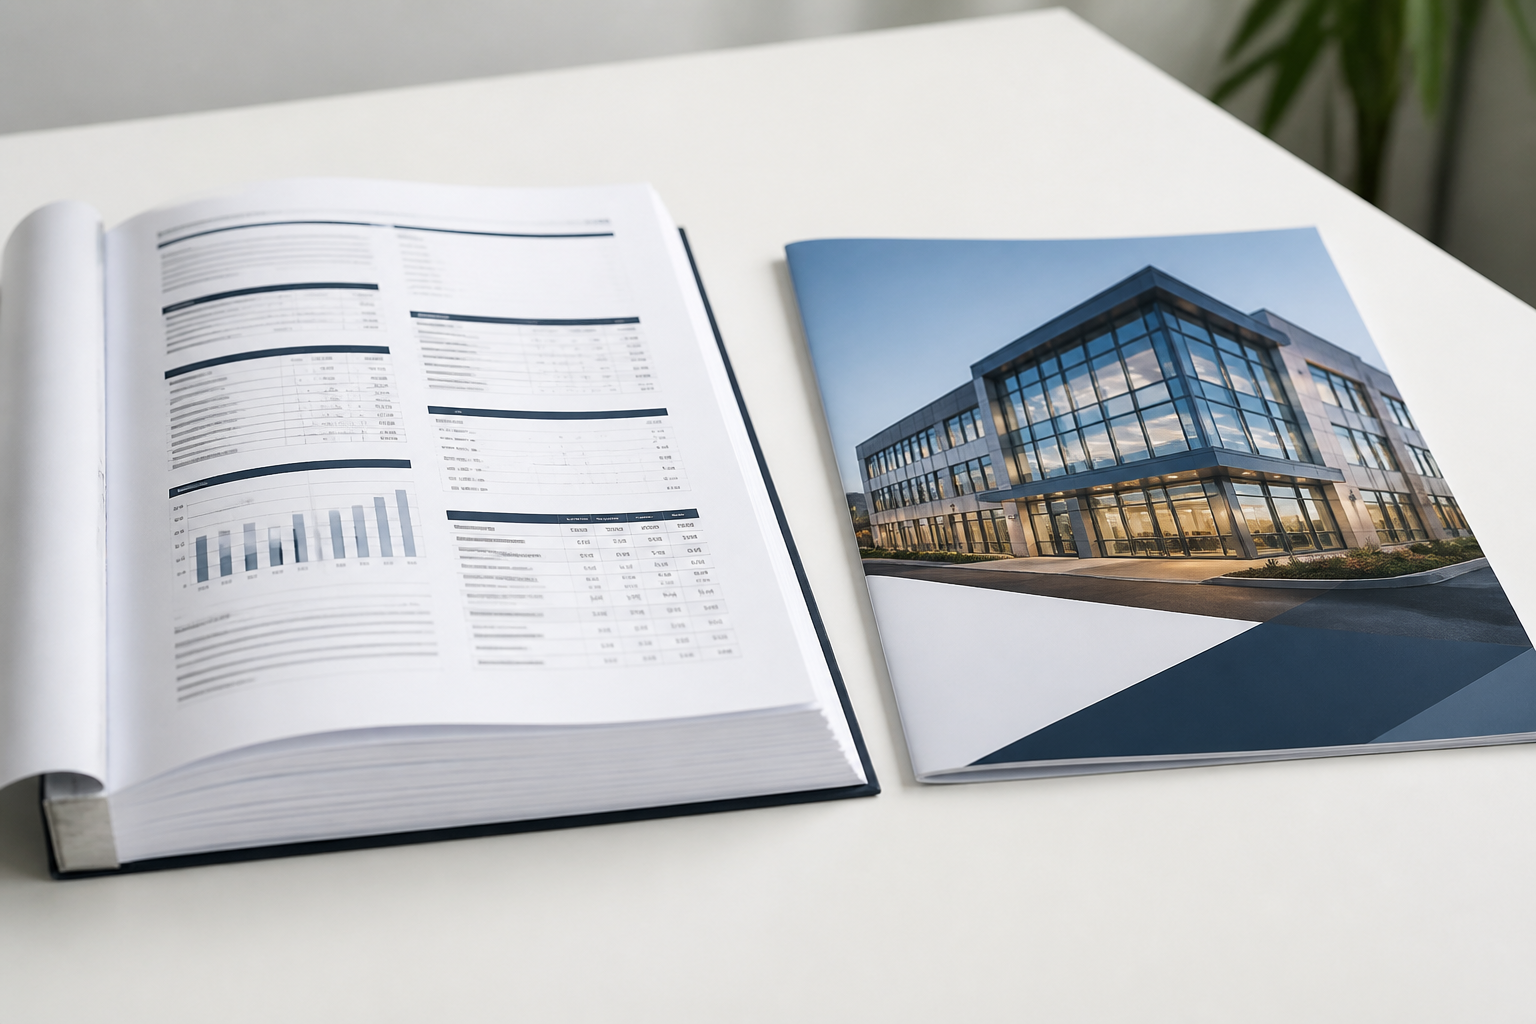
The short answer
An offering memorandum and a brochure are not competing formats. They serve different stages of the same process.
The brochure creates interest. It circulates widely, gets read in under a minute, and its job is to make a qualified buyer request more information.
The offering memorandum supports a decision. It goes to people who have already expressed interest, gets read carefully, and its job is to give an investor enough to underwrite the deal.
Confusion between the two produces the two most common document failures in commercial real estate marketing: a brochure so detailed nobody reads it, and a memorandum so thin nobody can underwrite from it.
If you only have time to get one right, get the memorandum right. It is the document that carries liability and closes deals.
What an offering memorandum does
The memorandum is the primary underwriting document. Typically 20 to 40 pages, sometimes considerably more for complex assets.
It exists to answer, in verifiable detail:
- What is the asset, precisely?
- What does it earn today, and on what basis?
- What could it earn, under what assumptions?
- Who are the tenants, and what are their terms?
- What is the market context?
- What are the risks?
- How does the offering process work?
Its readers are analysts and principals who will check the numbers. That audience shapes everything about it: financials shown as actuals and pro forma separately, assumptions stated explicitly, comparables detailed enough to verify, and disclaimer language that a lawyer approved.
A memorandum is also a liability document. Every figure is something a buyer may rely on, which is why the review process matters as much as the writing. Our offering memorandum checklist covers that review, and how to create an offering memorandum covers the content.
What a brochure does
The brochure, sometimes called a flyer, teaser, or one-pager depending on length and purpose, is a marketing document. One to four pages.
It exists to make someone want the memorandum. That means:
- A strong image and clear identification of the asset
- Location and asset type
- Headline metrics: size, price if disclosed, cap rate, occupancy
- Three or four reasons to be interested
- A clear next step and contact
Its readers are skimming. A broker forwards it, someone opens it on a phone between meetings, and it either registers in fifteen seconds or it does not. Density is the enemy.
The most common mistake is treating the brochure as a compressed memorandum. Cramming a rent roll onto page two does not make it more persuasive; it makes it unreadable at the moment it is actually being read.
The differences that actually matter
Purpose. The brochure generates qualified interest. The memorandum supports underwriting.
Length. One to four pages versus twenty to forty.
Reading time. Under a minute versus thirty minutes or more.
Audience. Broad circulation, including brokers and marginally qualified parties, versus a filtered set of serious prospects.
Financial depth. Headline metrics only versus full operating statements, pro forma, and stated assumptions.
Confidentiality. Freely distributed versus often gated behind a confidentiality agreement.
Liability exposure. Low but not zero versus high, with full disclaimer language required.
Update frequency. The brochure changes rarely; the memorandum is revised whenever pricing or assumptions change.
Design emphasis. Visual and immediate versus structured and navigable.
The practical implication of that last pair: the brochure is nearly static, while the memorandum needs a workflow that handles revisions cleanly. If your brochure and memorandum are maintained separately, a late pricing change means updating both and remembering to do so.
When you need both
For most investment sale assignments, you need both, and they should launch together.
Both, definitely:
- Investment sales of any meaningful size
- Multi-tenant assets where tenancy detail matters
- Value-add deals requiring a pro forma
- Confidential offerings where the teaser circulates and the memorandum is gated
- Anything marketed to institutional buyers
Brochure alone may be enough:
- Leasing assignments, where a flyer plus a floor plan is conventional
- Small owner-user properties sold to a local buyer
- Land listings where the story is simple
- Assets under a value threshold where a full memorandum is not worth the production time
Memorandum alone, rarely. Even a targeted off-market process benefits from a one-pager for the initial conversation.
The judgment call sits with mid-sized assets. A useful test: if a buyer would need a spreadsheet to evaluate the deal, they need a memorandum.
Confidentiality considerations
This is where the two documents intersect most dangerously.
The standard structure is that the brochure circulates freely and the memorandum follows a signed confidentiality agreement. That only works if the brochure genuinely omits what the confidentiality agreement is meant to protect.
Check specifically for:
- Tenant names in text, image captions, or chart labels
- Rent figures that would let someone back into lease economics
- Occupancy or income detail beyond what you intend to disclose
- Photographs showing tenant signage when tenancy is confidential
- Document metadata, which frequently retains the source file name or author
Redacted versions produced by hand are where leaks happen. Someone copies the memorandum, deletes the sensitive pages, and misses a figure in a summary chart. Generating both versions from the same underlying data with disclosure rules applied at output is considerably safer than editing a copy.
Producing both from one dataset
Here is the operational point that makes the whole distinction manageable.
The brochure and the memorandum contain overlapping information at different depths. The asset, the location, the headline financials, the highlights, and the contact block appear in both. Produced independently, that overlap is duplicated work and a permanent consistency risk.
Produced from one structured listing record, the overlap is free. The record holds the property fundamentals, tenancy, financials, market data, media, and narrative once. The memorandum renders it at full depth. The brochure renders a defined subset. A pricing change updates both.
This matters most on the day it usually goes wrong: the seller adjusts the asking price 48 hours before launch, and someone has to update the memorandum, the brochure, the property website, and the email. Manual workflows lose one of them, and the one they lose is usually the brochure, which is the document that circulates most widely.
Offering memorandum software covers generating both from shared data, and AI-powered commercial real estate marketing software extends the same record to the website, campaign, and social assets.
For the structural detail of each document, see our offering memorandum template outline, and common OM mistakes for the errors that survive into circulated versions.
The quickest way to see whether shared-data production works for your team is to generate both documents from one listing and compare them line by line. Try with one listing or book a demo and bring an asset with confidential tenancy, which is the harder test. More detail on Offering memorandum software.
Ready to see this on one of your listings?
Continue to Antela's Offering memorandum software — or try the workflow with one listing and book a demo when you're ready.
Frequently asked questions
Can a brochure replace an offering memorandum?
Only for simple, low-complexity assets marketed to a broad audience, such as small owner-user properties or straightforward leasing opportunities. Anything where an investor needs to underwrite income, tenancy, and risk requires the depth of a memorandum. A brochure that tries to serve both purposes usually ends up too long for casual readers and too thin for serious ones.
Should the brochure include pricing?
It depends on the offering strategy. Publicly marketed assets typically include the asking price in the brochure because it filters unqualified interest early. Confidential offerings or best-and-final processes often omit pricing entirely and direct interested parties to execute a confidentiality agreement first.
Which document goes out first?
The brochure or teaser, almost always. It circulates broadly to generate qualified interest, and the memorandum follows for parties who engage, often after a confidentiality agreement is executed. Both should be ready before launch, since a teaser that generates interest you cannot immediately serve wastes your best window.
Related Reading
More in Offering MemorandumOffering Memorandum
Your OM Isn’t a One-Time Project: The Hidden Cost of Keeping CRE Marketing Up to Date
Commercial real estate marketing is often priced as a one-time production job. In reality, every deal change can force updates across the OM, flyer, listing page, and campaign—and that operational cost is larger than the agency invoice.
Offering Memorandum
How to Create an Offering Memorandum
A step-by-step guide to creating a commercial real estate offering memorandum: structure, data gathering, financials, design, review, and disclaimers.
Offering Memorandum
Offering Memorandum Template
A section-by-section offering memorandum template for commercial real estate, with page counts, asset-type variations, and what to keep dynamic.
Offering Memorandum
Offering Memorandum Checklist
A pre-send offering memorandum checklist covering source data, content, financial reconciliation, brand consistency, legal language, and final review.
Offering Memorandum
Common OM Mistakes
The offering memorandum mistakes that cost CRE deals credibility: reconciliation errors, buried theses, stale data, weak disclaimers, and version chaos.